Concora Credit

Screenshots
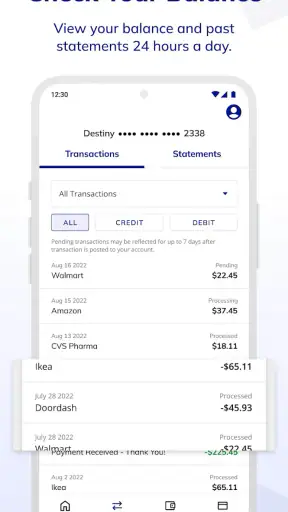
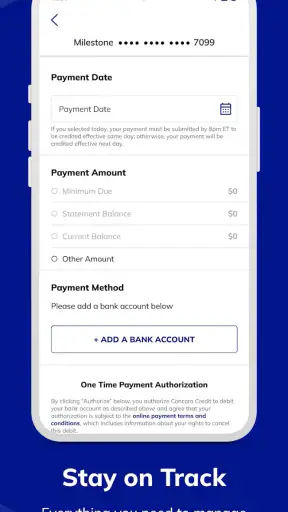
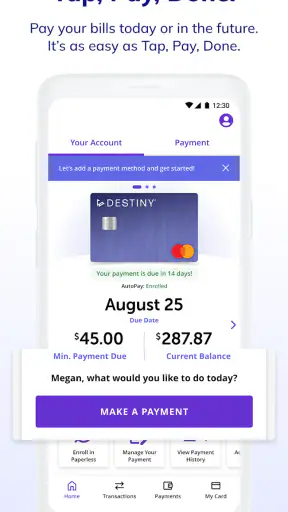
Details
- Rating
- 1.69K reviews
- Version
- 3.0.17
- Developer
- Concora Credit
Analysis by Norviv
Managing a credit account from a phone sounds simple until you need to check a balance quickly, review recent activity, or make sure a payment has been handled before a busy day gets away from you. I spent time using Concora Credit as a mobile finance tool, and my impression is that it works best when treated as a focused account-management companion rather than a complete personal-finance system. It keeps attention on the Concora account relationship, which can be a real advantage for someone who wants fewer distractions.
The app is free to install, is intended for everyone, and comes from Concora Credit. It belongs to the finance category and has built a sizeable audience, with more than a million installs and an average score of 3.4 from roughly three and a half thousand ratings. That combination tells me the app is useful to many account holders, but not universally smooth. My experience reflects that balance: the core purpose is clear, while the value depends heavily on whether you already have a Concora Credit account and what you expect a mobile finance app to do.
Using Concora Credit as a dependable account routine
I find it helpful to treat the app as one checkpoint in a wider money routine, not as the routine itself. Before opening it, I decide what I need to verify; afterward, I note any decision that affects my budget so the account view has useful context. That habit also makes it easier to tell ordinary sign-in friction from a problem that needs a different kind of fix.
The baseline workflow is deliberately narrow
The most sensible way to use the app is to begin with one repeatable question: “What do I need to know about my Concora account right now?” Instead of opening a broad budgeting platform, connecting several banks, or searching through email, I use the dedicated app to go straight to account information. That focused workflow is its main strength.
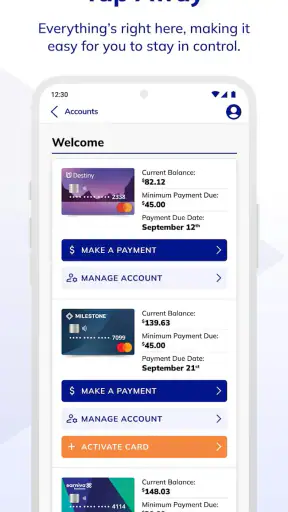
On a normal day, I would open the app to check the current account position, look over recent activity, and confirm whether anything needs attention. The important habit is not to browse aimlessly. I first identify the task, then leave once it is complete. That makes the app more useful than it might appear from its short store description, because a consistent two-minute check can be easier to maintain than a larger financial-planning routine.
A realistic example is a purchase made near the end of the month. Before deciding whether another expense fits comfortably, I can open Concora Credit, review the account information available there, and use that as one part of my decision. I would not treat the screen as a replacement for a full household budget, but it gives me a direct way to check the account connected to the app instead of relying on memory.
That distinction matters. Concora Credit is not the same kind of tool as a general budgeting app that gathers bank accounts, categorizes spending across providers, and produces a complete financial picture. Its narrower scope can feel reassuring when I only need account access. It can also feel limiting when I want to compare this account with checking, savings, loans, or cards held elsewhere.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
What the app is good at for everyday account holders
I see the app as most useful for people who already manage their Concora relationship and want a practical mobile entry point. It can reduce the need to use a desktop browser for basic account tasks and makes checking information part of an ordinary phone routine. That is especially helpful for someone who prefers to review an account immediately rather than postpone it until they are near a computer.
The best use case is a short, repeatable check before a payment decision. I might open the app in the morning, confirm the account details I need, and close it before moving on. Another useful moment is after making a payment or transaction: checking again later can help me keep my own records aligned with what appears in the account interface. I still keep important confirmations and personal notes separately, but the app provides a convenient place to look.
Concora Credit also suits users who dislike financial apps overloaded with charts, recommendations, and unrelated services. The focused design makes the purpose easy to understand. If my only goal is managing a Concora account from a smartphone, that simplicity is more valuable than a large collection of budgeting tools I would never use.
However, someone without a Concora Credit account has little reason to install it. The app is not a general-purpose money manager where any user can start tracking expenses independently. Likewise, users who need detailed spending categories, shared household planning, investment monitoring, or consolidated balances should look at a broader finance solution instead of expecting this app to grow into one.
Settings and account habits worth checking
My first recommendation is to spend a little time reviewing the app’s available account and notification settings after signing in. I do not assume that every alert is equally useful. If the app offers choices about account activity or reminders, I would keep the messages that help me act and reduce anything that merely creates noise. The goal is to make the app a prompt for a real task, not another source of interruptions.
I also check that the account information shown in the app matches the account I intend to manage before relying on it during a rushed moment. This is a small but important habit for anyone with more than one account relationship. A clear mental label—such as remembering which account I am checking before opening the app—reduces the chance of treating the wrong screen as the answer to a payment question.
Security habits matter just as much as convenience. I use the official sign-in process, avoid entering credentials while connected to an untrusted network, and do not leave sensitive account screens open when handing my phone to someone else. These are not special Concora features; they are sensible practices for any finance app. The advantage of a dedicated account app is that it encourages me to access the account directly, but it does not remove the need for careful phone security.
I would also avoid turning every alert into an emergency. A notification can tell me that something deserves a look, but I still open the account and read the relevant details before making a decision. That habit is particularly useful when a message is brief or arrives at an inconvenient time. The app works best when it supports judgment rather than replacing it.
Faster patterns for repeat users
Experienced users can make the app feel quicker by assigning it a specific place in their routine. I prefer opening it at a predictable point—before reviewing my monthly obligations, after a significant account event, or when I am checking whether a planned purchase fits. A fixed trigger is more reliable than waiting until I vaguely remember that I should look.
Another useful pattern is to separate “checking” from “record keeping.” I use the app for the current account view and my own notes or budget for the wider picture. That prevents me from repeatedly reopening the app to answer questions it is not designed to answer, such as how the account compares with all other household expenses. The result is a faster workflow because each tool has a clear job.
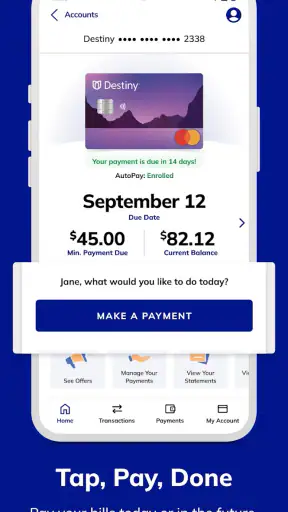
I would also avoid making a payment decision from a single glance if the timing is important. Instead, I check the account, review the recent activity that matters, and confirm the action through the appropriate in-app flow. If I need proof for my records, I save the confirmation in whatever personal system I already use. This three-step pattern—inspect, act, document—is more dependable than opening the app, tapping quickly, and assuming the task is finished.
For people who use multiple Concora accounts, the practical shortcut is mental organization rather than a clever trick. Before opening the app, I decide which account question I am asking. After signing in, I verify the account context before acting. That takes only a moment, but it is a valuable trade-off: a slightly slower first glance can prevent a much more frustrating correction later.
The current release is version 3.0.17, and the app supports devices running Android 7.1 or later. I would still keep the application updated through the normal app-store process, because finance tools are not the place where I want to remain on an old build unnecessarily. At the same time, I would not assume that an update alone changes the basic role of the product. Its central purpose remains account management, so the best speed gains come from good routines rather than expecting a completely different experience after every update.
Where the limits become noticeable
The biggest limitation is scope. Concora Credit gives me a direct way to manage the Concora account experience, but it does not replace a complete financial dashboard. If I want to see spending across several institutions, build detailed categories, set household targets, or analyze long-term cash flow, I need another tool or a separate personal system.
That narrow focus also affects how I interpret the app’s rating of 3.4. I would not read that score as proof that the app is unusable, nor would I treat it as a guarantee of a flawless experience. Mobile finance apps are judged during high-pressure moments—when someone is trying to verify a payment, understand an account change, or sign in quickly. Small points of friction matter more in those situations than they would in a casual entertainment app.
For that reason, I would test the basic workflow before depending on it for an urgent deadline. Open the app when you have time, sign in carefully, locate the account information you normally need, and become familiar with the route to the relevant action. Doing that early is a practical safeguard. If access becomes difficult later, at least you will know whether the problem is unfamiliarity, account access, or something that needs support from Concora Credit.
I also would not use the app as my only record of important financial activity. A mobile account screen is convenient, but personal records can help when comparing transactions, planning a budget, or checking what happened over a longer period. Keeping a simple note of significant payments and decisions gives me context that a focused account-management app may not provide on its own.
Who should choose it, and who should skip it
I would recommend Concora Credit to an existing customer who wants straightforward mobile access to a Concora account and prefers a focused interface over a broad money-management platform. It is also a reasonable choice for someone building a short daily or weekly account-checking habit, provided they understand that the app is centered on Concora rather than their entire financial life.
I would be more cautious about recommending it to a person choosing a finance app for the first time without a Concora relationship. There is no benefit in adding a specialized account tool when the real need is expense tracking or multi-bank budgeting. In that situation, a general finance app, a bank’s own application, or even a carefully maintained spreadsheet may be a better match.
I would also steer away from relying on it alone if your main requirement is advanced analysis. A budgeting service that combines accounts may be more efficient for comparing obligations, while a bank app may be preferable when most of your activity happens with that bank. Concora Credit makes sense when the Concora account is the center of the task—not when it is only one small item in a much larger financial picture.
My verdict after building a repeatable workflow
After using it as intended, I see Concora Credit as a practical specialist rather than an all-in-one financial assistant. Its strongest quality is directness: I can approach the app with a specific Concora account question and avoid the clutter of a broader platform. The free price and everyone age rating also make it easy for eligible users to try without adding a purchase decision to the process.
My recommendation comes with a clear condition: use it alongside sensible habits. Check the account before important decisions, review the available settings so alerts remain useful, verify the account context before acting, and keep separate notes for the wider budget. Those habits turn a basic mobile access point into a reliable part of a financial routine.
In the end, I would choose Concora Credit for focused account management and skip it as a replacement for budgeting, banking across several institutions, or long-term financial planning. It has reached more than a million installs, yet its moderate average rating reminds me to approach it realistically rather than expecting every interaction to be effortless. The right question is not whether it does everything, but whether it makes your Concora account easier to manage. For the right user, that focused role is enough to make it worthwhile.
Frequently Asked Questions
01What is Concora Credit, and how does it work?
Concora Credit is a consumer financing service that allows eligible shoppers to apply for credit through participating retail partners, often when purchasing products such as furniture, electronics, appliances, or other household items. After an application is submitted, Concora Credit reviews the applicant’s information and may provide available financing options. Approval, credit limits, payment terms, and promotional offers depend on individual creditworthiness and the specific retailer program.
02Is the Concora Credit app safe and legitimate to use?
Concora Credit is associated with retail financing programs and provides account-management tools for customers with an eligible credit account. As with any financial application, users should download it only from the official Google Play Store or Apple App Store and verify the developer name before signing in. Avoid sharing passwords, security codes, or personal information through unofficial links, and review the privacy policy and account-security guidance before using the service.
03What can I do with the Concora Credit app?
Depending on your account and the features currently available, the Concora Credit app may let you review your balance, check recent transactions, view statements, monitor payment due dates, and make payments. Some users may also be able to manage account details or contact customer support. Available tools can vary by credit program, retailer, device, and account status, so the app should be treated as a convenient account-management option rather than a guarantee that every service is available to everyone.
04Does Concora Credit charge interest or fees?
Concora Credit financing terms vary according to the retailer, credit product, promotional offer, and the applicant’s approved agreement. Some purchases may include deferred-interest or promotional financing, while others may involve an annual percentage rate or additional charges. Carefully read the credit agreement, payment schedule, minimum-payment requirements, late-payment policy, and any applicable fees before accepting an offer. Making only the minimum payment may not be enough to avoid interest or satisfy promotional conditions.
05What should I check before applying for Concora Credit?
Before applying, confirm that the financing option is offered by the retailer you are using and review the complete terms rather than relying only on promotional advertising. Check the APR, total repayment amount, payment frequency, promotional expiration date, credit requirements, and consequences of missed payments. You should also consider whether the monthly payment fits your budget, since applying may involve a credit inquiry and approval is not guaranteed.


